Running Bear's Coffee Shop July 2024

ModelRailroadForums.com is a free Model Railroad Discussion Forum and photo gallery. We cover all scales and sizes of model railroads. Online since 2002, it's one of the oldest and largest model railroad forums on the web. Whether you're a master model railroader or just getting started, you'll find something of interest here.


Status
Not open for further replies.
Here's the page on the current programs people might qualify for loan forgiveness, most after 10 years of payment in good standing.


Teachers
Healtcare workers
Govt employees
Some military folks
NonProfit workers who worked in the sector for 10 years
And... Those who were taken advantage of by diploma mills and were misrepresented by those institutions.
That one is a pet peeve of mine.... no educational program should be misleading students, and helping them get into debt, then bailing on them with nonaccredited education, or closing early and leaving the students high and dry without transferable credits....

This is getting a LOT of hype on certain media outlets. I suggest anyone with strong feelings read more about who and what Congress decided to pass forgiveness on to.

We'll probably have to agree to disagree on this. But these were Bush/Clinton/Bush2 programs. The current admin just cut a lot of the red tape that was slowing this down (or in the case of the woman I mentioned last month who was screwed by her loan administrator, and was 12c in arrears each year because of their rounding error, corrected corporate "errors" designed to keep their books full of payees.)
 
PS:
Happy Canada Day to all the Canadian Coffee Shoppers
Canada Day.jpg
 
Actually, in most of the cases, the borrower has already paid back most if not all of the money they borrowed from the fed govt.

It's Mostly the interest that is in question.

Let's take a hypothetical with the program I referenced

If "Sally" were to borrow 30K to go work on a degree... and her payments came out to $200/mo on a 20 year note (4.66% interest). Base on that payment, if the Fed Govt weren't collecting interest on that amount, it would be paid off in 12 years. Not 20.

It's not as simple as "someone has to pay". It's how much of the interest is being cancelled in most cases.

It'll probably take a good 6 mos or so for that forgiveness to get approved (moving at the speed of government). And Sally would keep paying her required amount or jeopardize the foregiveness. So, in 126 mos of paying, the fed govt recovers 25,200 of the original 30K. And they reward a vet (in some cases) or steer people into professions that they deemed worthy of supporting with the program (teachers, first responders, etc).

Interest is part of the loan. Someone has to pay. There is an opportunity cost associated with loaning money and the interest makes up for that lost opportunity. Loans aren't free. "Debt forgiveness" is shifting that cost to the taxpayer and not those who willingly signed on the dotted line. Its called "responsibility."

I don't have data but I also doubt a lot of those who would be affected have already paid enough to cover the principal. No doubt that is true in some cases.
 
Last edited:


Here's the page on the current programs people might qualify for loan forgiveness, most after 10 years of payment in good standing.


Teachers
Healtcare workers
Govt employees
Some military folks
NonProfit workers who worked in the sector for 10 years
And... Those who were taken advantage of by diploma mills and were misrepresented by those institutions.
That one is a pet peeve of mine.... no educational program should be misleading students, and helping them get into debt, then bailing on them with nonaccredited education, or closing early and leaving the students high and dry without transferable credits....

This is getting a LOT of hype on certain media outlets. I suggest anyone with strong feelings read more about who and what Congress decided to pass forgiveness on to.

We'll probably have to agree to disagree on this. But these were Bush/Clinton/Bush2 programs. The current admin just cut a lot of the red tape that was slowing this down (or in the case of the woman I mentioned last month who was screwed by her loan administrator, and was 12c in arrears each year because of their rounding error, corrected corporate "errors" designed to keep their books full of payees.)

That's the wrong list for the latest program. That is a separate program in addition to the debt relief, which is for "loand and middle income" loan recipients. (See the PSLF below)

This is not just cutting through the red tape of BUSH/CLINTON/BUSH2 era programs. There may be some of that but this is a new program (and is only a shell of what they wanted to do but were slapped down by courts)

----

Part 2. Providing targeted debt relief to low- and middle-income families​

To smooth the transition back to repayment and help borrowers at highest risk of delinquencies or default once payments resume, the U.S. Department of Education will provide up to $20,000 in debt relief to Pell Grant recipients with loans held by the Department of Education and up to $10,000 in debt relief to non-Pell Grant recipients. Borrowers are eligible for this relief if their individual income is less than $125,000 or $250,000 for households. Get details about one-time student loan debt relief.
In addition, borrowers who are employed by nonprofits, the military, or federal, state, Tribal, or local government may be eligible to have all of their student loans forgiven through the Public Service Loan Forgiveness (PSLF) program. For more information on eligibility and requirements, go to PSLF.gov.

Frequently Asked Questions​

How do I know if I am eligible for debt relief?
  • To be eligible, your annual income must have fallen below $125,000 (for individuals) or $250,000 (for married couples or heads of households).
  • If you received a Pell Grant in college and meet the income threshold, you will be eligible for up to $20,000 in debt relief.
  • If you did not receive a Pell Grant in college and meet the income threshold, you will be eligible for up to $10,000 in debt relief.
What does the “up to” in “up to $20,000” or “up to $10,000” mean?
  • Your relief is capped at the amount of your outstanding debt.
  • For example: If you are eligible for $20,000 in debt relief, but have a balance of $15,000 remaining, you will only receive $15,000 in relief.
What is the Public Service Loan Forgiveness Program?
  • The Public Service Loan Forgiveness (PSLF) program forgives the remaining balance on your federal student loans after 120 payments working full time for federal, state, Tribal, or local government; the military; or a qualifying non-profit. Learn more about PSLF and apply.
  • Temporary changes, which ended on Oct. 31, 2022, provided flexibility that made it easier to receive forgiveness by allowing borrowers to receive credit for past periods of repayment that would otherwise not qualify for PSLF.
  • A borrower who missed the limited PSLF waiver deadline has one more chance to have their payment count corrected. Learn more about the opportunity for the one-time account adjustment.

---

Isn't that one being challenged in court? Or about to be?
 
I think you'll see less pushback and resistance to programs that help veterans, or that can cancel (some) loan debt in exchange for a period of public service, or work in certain needed sectors that can't find enough people to work in them. The debtors still have skin in the game through a time commitment etc.
 
I think you'll see less pushback and resistance to programs that help veterans, or that can cancel (some) loan debt in exchange for a period of public service, or work in certain needed sectors that can't find enough people to work in them. The debtors still have skin in the game through a time commitment etc.
Unfortunately, this thread proves that incorrect.
 
I don’t fall into believing this is vote buying.

I have a niece that was just forgiven her college debt and has never voted and says she won’t.

This came up in a conversation at dinner a few weeks ago at one of my golf events. Many of these guys have their own businesses and vote red. Of the 60+ at dinner more than 1/2 seemed to be in favor of canceling the loans because it puts less pressure on them to raise salaries!

My opinion is, you knew getting the loan it was debt to be paid back, so pay it…


Now, if only we could go after all of those PPP loans that were forgiven ... Especially those of congress-critters and administration members on both sides of the aisle.

In good news, it'll be NY Strip steak for dinner tonight. Hoping the wife will make cornbread to go with it.

Tomorrow I'm going to try the smoked meatloaf recipe.
 
Unfortunately, this thread proves that incorrect.
Not really. Most of the pushback is most likely related to the blanket forgiveness like I mentioned as that is mostly what has been in the news the past year or three. That's what most people, I assume, are associating with "student loan forgiveness" and not older programs, even if those older programs also forgave loans and are being restructured today.

In other words, I am guessing that most people who have heard recently about "studetn loan forgiveness" have heard about the blanket forgiveness attempted or being attempted by Biden. So the pushback would logically be about those efforts.

I'm not saying there wouldn't be pushback about older programs but they've been around a long time without a lot of so-called pushback or even presence in the knowledge of the average person. But everyone has heard on the news about the blanket forgiveness, which is not about people who've paid the principal but are stuck with the interest, etc. And it's mnot pushback about GI Bill or other benefits.
 
I don’t fall into believing this is vote buying.

I have a niece that was just forgiven her college debt and has never voted and says she won’t.

This came up in a conversation at dinner a few weeks ago at one of my golf events. Many of these guys have their own businesses and vote red. Of the 60+ at dinner more than 1/2 seemed to be in favor of canceling the loans because it puts less pressure on them to raise salaries!

My opinion is, you knew getting the loan it was debt to be paid back, so pay it…

It is vote buying pure and simple. The vote buyers don't check the voting history (or lack there of) of any individual person so someone who has their student loan debt forgiven who has never voted is not evidence against it being vote buying.

Circumstantial evidence supports the notion: These proposals tend to come out closer to elections (and not off years) and also tend to target known groups of voters who are assumed to tend to vote in a specific block. And lots of other circumstantial evidence.
 
Now, if only we could go after all of those PPP loans that were forgiven
I'm not in favor of those being forgiven but there is a huge difference: Those were designed to be forgiven. Their structure and the whole system was designed around a "loan" that would be forgiven as long as the criteria were met. It's not after the fact.

The misuse of the program was a failure of its administration.

Looking quickly it appears that the amount of fraudulent funds from PPP and EIDL loans was about 17% disbursed. FYI


Good evening all,

Trying to catch up again. I'm not getting much anytime to do anything other than care provider these days. Just getting the yard mowed goes down as a major accomplishment. A neighbor came up this morning to look after my wife so I could make a Costco run.

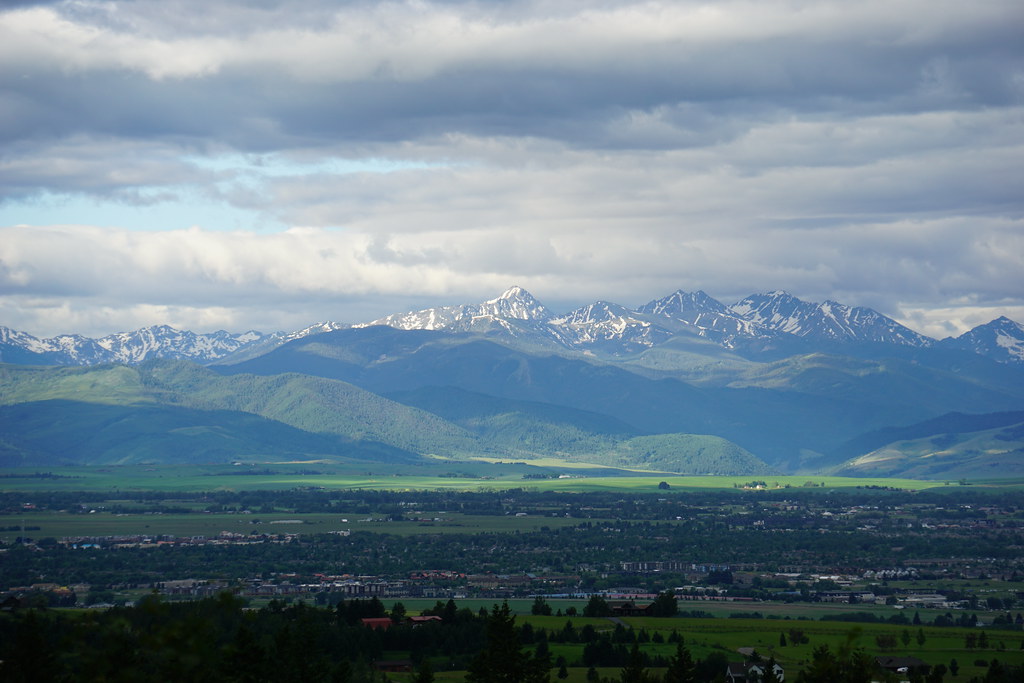
On the positive side, yesterday produced about 1.3" of needed rain. Photo from Friday.
53826033500_1229101efa_b.jpg
 
Status
Not open for further replies.


Affiliate Disclosure: We may receive a commision from some of the links and ads shown on this website (Learn More Here)

Back
Top